ByJohn A
Dual Currency Deposit Products: A Practical Introduction
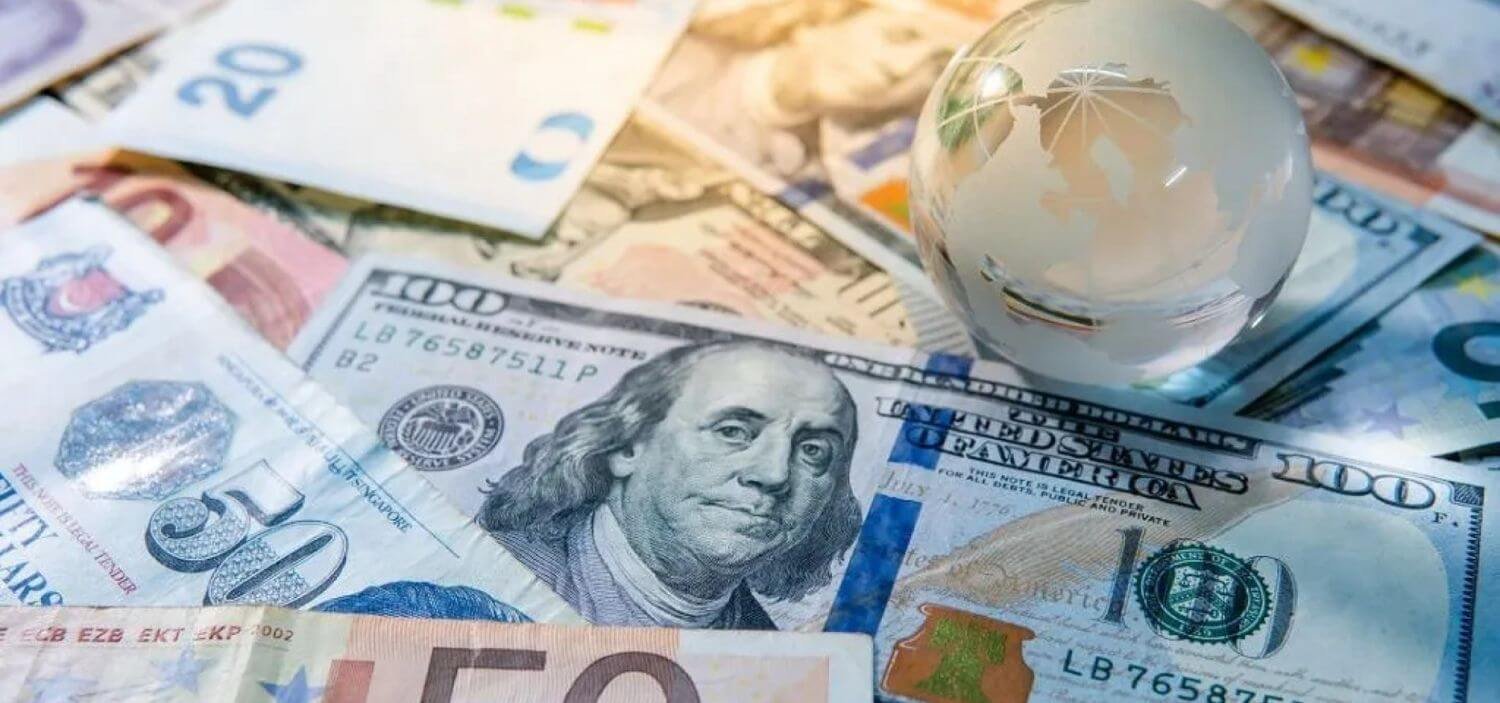
A dual currency deposit shares similarities with standard fixed deposits while introducing a foreign exchange element that can affect the currency in which principal and yield are ultimately returned, making it a distinct product category worth understanding on its own terms.
Comparing Dual Currency Deposits to Standard Fixed Deposits
Unlike a standard fixed deposit, which returns principal and interest in the same currency deposited, a dual currency deposit carries the possibility of conversion into an alternative currency at maturity, depending on how exchange rates move relative to a predetermined strike level.
The Role of the Strike Rate in Determining Outcomes
The predetermined strike rate embedded within a dual currency deposit structure determines the threshold at which conversion into the alternative currency becomes triggered, making a clear understanding of this mechanism essential before committing funds.
Time Horizon Considerations for Dual Currency Deposits
These products typically involve a fixed maturity date, meaning investors should ensure the committed timeframe aligns with their broader liquidity needs, since early withdrawal before maturity may not be straightforward or may involve unfavorable terms. Those researching this product category can review detailed mechanics at dual currency deposit where structure and terms are outlined.
Understanding the Full Risk Profile Before Committing Funds
Prospective depositors should ensure they fully understand the potential currency conversion outcome and are comfortable with either possible result before committing funds to this type of structured deposit product.
Common Questions
How does a dual currency deposit differ from a standard fixed deposit? Unlike a standard fixed deposit returning the same currency deposited, a dual currency deposit carries potential conversion into an alternative currency at maturity based on exchange rate movements.
What is the strike rate in a dual currency deposit? The strike rate is the predetermined exchange rate threshold that determines whether conversion into the alternative currency is triggered at maturity.
Can I withdraw funds from a dual currency deposit before maturity? Early withdrawal before maturity may not be straightforward or may involve unfavorable terms, making it important to align the deposit term with your actual liquidity needs.
See also: How to Research a Cryptocurrency Before Investing
Conclusion
Dual currency deposit products offer a distinct structured alternative to standard fixed deposits, involving genuine foreign exchange risk that requires careful understanding before committing funds. This overview is general in nature and does not constitute financial advice; prospective depositors should consult a qualified financial advisor to assess suitability for their specific circumstances.